


When ownership shifts without warning, your business faces risks few plan for. An unexpected death, incapacity, or partner exit can stall operations and trigger disputes that threaten stability. Estate planning for business owners offers tools like buy-sell agreements and trusts that keep your company running smoothly when control changes hands. Read on to learn how practical steps can protect your business and safeguard its future.
Essential Estate Planning Tools
When it comes to protecting your company’s future, having the right estate planning tools is important. These tools ensure that your business remains stable despite unexpected changes in ownership.
Buy-Sell and Shareholder Agreements
A buy-sell agreement is a key component for any business owner. It outlines what happens to a partner’s share if they exit the company. This agreement can prevent disputes by setting clear terms for buyouts. For example, if a partner passes away, the agreement might allow remaining partners to buy the deceased’s share. This way, you maintain control over who owns parts of your business. Shareholder agreements work similarly, providing rules for decision-making and ownership transfers. With these agreements, you ensure your business remains under trusted control.
Power of Attorney for Business Owners
A power of attorney is another vital tool. It allows you to designate someone to make decisions on your behalf if you’re unable to do so. This could be due to illness or absence. Having a power of attorney means your business operations can continue smoothly. This person can handle tasks like signing contracts or managing finances. Choosing a trusted individual for this role is essential, as they will act in your best interest.
Business Interests in a Trust
Placing business interests in a trust can protect your company. A trust allows you to specify how your business assets are handled. It can provide instructions for management and succession. This is particularly useful in family businesses, where you might want to keep ownership within the family. Trusts can also offer privacy and reduce probate delays. By setting up a trust, you ensure your business follows your wishes even when you’re not around.
Strategies for Unexpected Ownership Changes
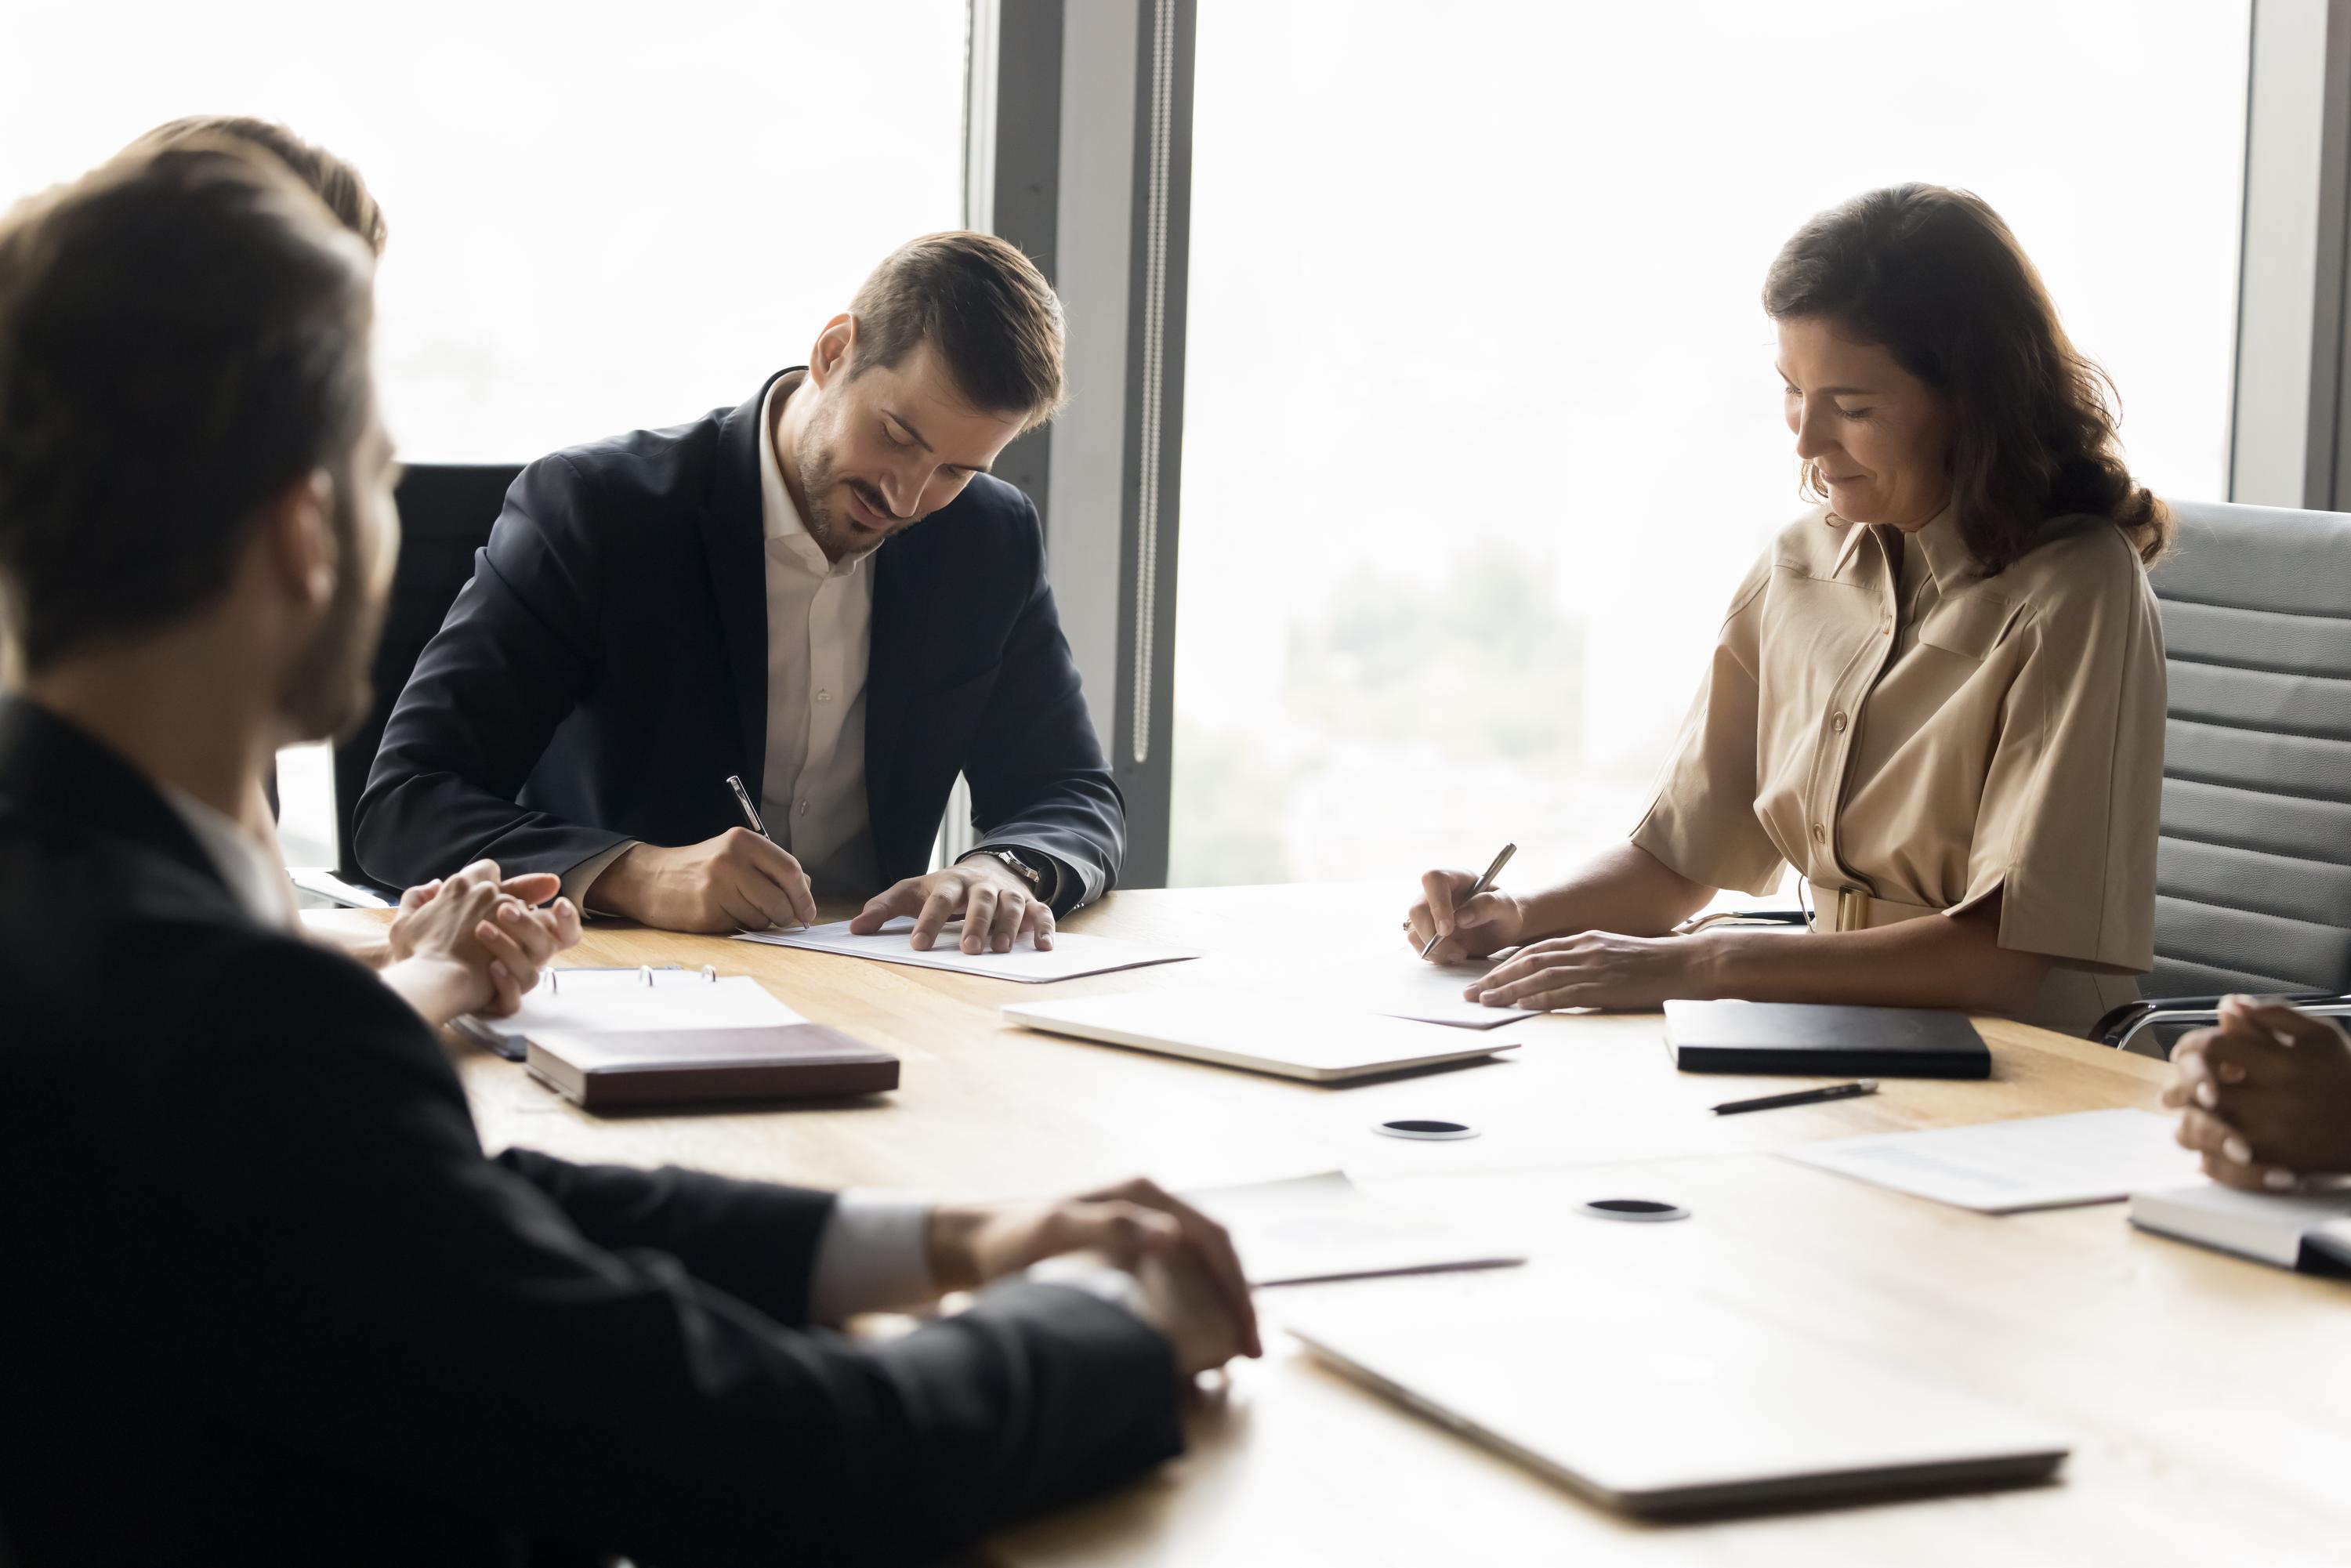
Planning for unexpected changes is smart business. These strategies help you navigate situations where ownership shifts without warning.
Valuation Methods for Buyout
Knowing your business’s value is essential. It guides buyouts if a partner leaves. There are different ways to determine this value: asset-based, income-based, or market-based approaches. Each has its benefits. For instance, an asset-based approach might be best for a company with significant physical assets. Accurate valuation ensures fair transactions and minimizes disputes.
Key Person Insurance Coordination
Key person insurance provides financial protection. It covers potential income loss if a critical team member is unable to work. This insurance can be used to hire temporary help or cover business expenses. It ensures stability during challenging times. Coordinating this insurance with your overall business plan is important, as it complements other estate planning tools.
Right of First Refusal
This strategy allows existing partners to buy a departing partner’s share before outsiders. It helps maintain control within the current ownership group. Including this clause in your agreements adds an extra layer of protection. It prevents unwelcome changes and keeps business operations consistent.
Maintaining Business Continuity
Keeping your business running smoothly during ownership changes is vital. These steps help maintain continuity and reduce risks.
Operating Agreement Updates
Regularly updating your operating agreement is a must. This document outlines how your business operates and makes decisions. As your company evolves, so should this agreement. Updates might include new roles, responsibilities, or procedures. By keeping it current, you ensure everyone is on the same page and avoid potential conflicts.
Cross State Business Counsel
If your business operates in multiple states, having cross-state legal counsel is beneficial. Different states have different laws and regulations. Experienced counsel can help you navigate these complexities. This ensures your business remains compliant and reduces legal risks. It also offers peace of mind, knowing you have knowledgeable advisors on your side.
Probate Delay and Business Risk
Probate can delay business operations. It involves settling the deceased’s estate, which can take time. Planning can minimize these delays. Tools like trusts and clear agreements can bypass probate, keeping your business running. Addressing this risk proactively protects your company from potential disruptions.
Frequently Asked Questions
What is a buy-sell agreement, and why do I need one?
A buy-sell agreement is a legal document outlining how ownership shares are handled if a partner exits the business. It prevents disputes and ensures a smooth transition of ownership, keeping your business stable.
How does a power of attorney benefit my business?
A power of attorney allows you to designate someone to make decisions on your behalf if you’re unable to do so. This ensures continuous business operations, even if you’re absent or incapacitated.
What are business interests in a trust?
Placing business interests in a trust allows you to specify how your business assets are managed and transferred. It offers privacy, reduces probate delays, and ensures your wishes are followed, especially in family businesses.
Why is key person insurance important?
Key person insurance provides financial protection if a key team member cannot work. It helps cover income loss, hire temporary help, or manage business expenses, ensuring stability during challenging times.
How can I maintain business continuity during unexpected ownership changes?
Maintaining business continuity involves regularly updating operating agreements, having cross-state legal counsel, and planning to bypass probate delays. These steps reduce risks and keep your business running smoothly.